Samity and microcredit lending
Savings groups and small loans. An MRA certificate is compulsory, and new applications have been suspended since 4 November 2024. The service charge ceiling is 24 percent on the declining balance.
- Last reviewed: 19 September 2026
- Version 1
Samity and microcredit lending
- Starting capital
- ৳15,00,000 – ৳52,00,000 Editorial estimate
- Manpower
- 3 – 15 people
- First sale
- 35 – 70 days Editorial estimate
- Break-even
- 92 – 120 months Editorial estimate
- Kind of work
- Shop · Hard
About the business
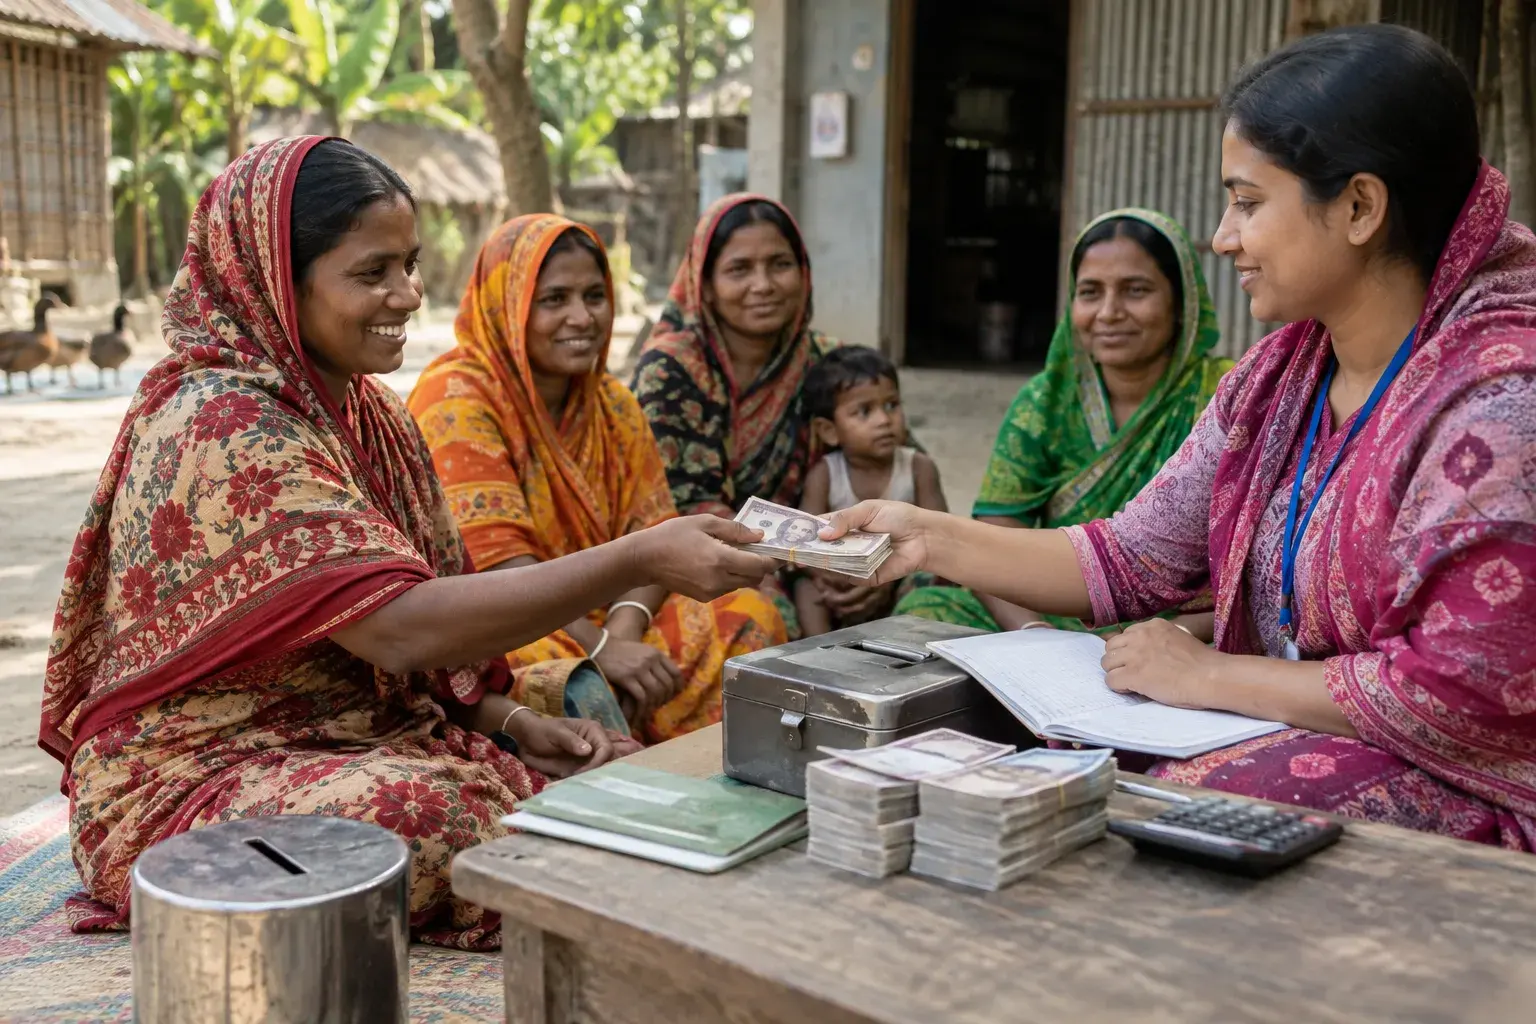
Forming a village samity, collecting savings and lending small sums is microcredit. It cannot be started at will. Section 15(1) of the Microcredit Regulatory Authority Act 2006 bars any institution from running microcredit activity without an MRA certificate, and section 35 makes doing so punishable by up to one year in prison, a fine of up to Tk 5 lakh, or both. More decisively, on 4 November 2024 MRA issued a public notice suspending the acceptance of new certificate applications until further order. That notice records 6,642 applications received in total, 898 certificates granted, 174 later cancelled, and 724 licensed institutions remaining. The economics of the licensed ones are thin. MRA Circular Letter 50 caps the service charge at 24 percent on the declining balance, so at most Tk 24 a year per Tk 100 of loan outstanding. Against that, MRA's June 2025 statistics show total operating cost per Tk 100 of average loan outstanding at Tk 16.17 for BRAC, Tk 14.67 for ASA, Tk 17.58 for BURO Bangladesh and Tk 19.59 for Shakti Foundation. Admission fee Tk 10, pass book Tk 10 and loan form Tk 5 are the only charges allowed, and deposits may be taken only from members. Portfolio quality is slipping: classified loans stood at 8.52 percent in June 2025, and loans overdue by 1 to 30 days jumped from 1.12 to 8.85 percent in a year.
Unit economics
| Item | Range | Evidence | Suggest a correction |
|---|---|---|---|
| Monthly working capital | ৳15,00,000 – ৳52,00,000 | Editorial estimate | |
| Selling price | ৳24 / unit | Official source | |
| Variable cost | ৳11 – ৳21 / unit | Official source | |
| Gross margin | 12% – 54% | Editorial estimate | |
| Time to first revenue | 35 – 70 days | Editorial estimate | |
| Break-even time | 92 – 120 months | Editorial estimate | |
| Cash cycle | 231 days | Editorial estimate | |
| Waste / loss | 4% – 9% | Official source | |
| Daily capacity | 80 – 275 | Editorial estimate |
What you need to start
- Member pass books, admission forms, loan forms, a collection register and a cash box. The undertaking for a small-enterprise loan must be executed on a Tk 200 non-judicial stamp.Equipment
- Trade licence from the city corporation or municipality: form Tk 10, licence book Tk 50, standard tax Tk 30, stamp Tk 150-300, licence fee Tk 100-60,000 by trade type.Licence
- Institutional registration with the Department of Social Services, the NGO Affairs Bureau, the Department of Women Affairs or the Registrar of Joint Stock Companies and Firms. MRA licenses registered institutions, not individuals.Licence
- MRA certificate. Under rule 15, up to 25,000 borrowers: certificate fee Tk 10,000, annual fee Tk 5,000. 25,000 to 1 lakh: Tk 25,000 and Tk 10,000. 1 lakh to 10 lakh: Tk 2,00,000 and Tk 15,000. Above 10 lakh: Tk 5,00,000 and Tk 25,000. New applications have been suspended since 4 November 2024.Licence
- Loan classification, loss provisioning and bookkeeping. Hard copies of the general ledger and cash book are compulsory, and the branch bank account runs on two authorised joint signatures.Skill
- Sources of funds: members' savings, own surplus, PKSF and commercial bank loans. Larger MFIs may finance smaller ones, but only under MRA's 2022 financing policy.Supplier
- A branch office and an approved working area. Rule 4(kha) bars working outside it; head office and branch addresses must be reported to MRA and any change notified in writing within one month.Workspace
How the work is done
- 1First find out whether a certificate is available at all. MRA has suspended new applications since 4 November 2024. Check the current position on hotline 16133 or at mra.gov.bd before spending a taka.
- 2MRA licenses institutions, not individuals. Register the organisation first with the Department of Social Services, the NGO Affairs Bureau, the Department of Women Affairs or the Registrar of Joint Stock Companies and Firms.
- 3Fix your working area and state it in the application. Rule 4(kha) forbids operating microcredit outside the approved working area.
- 4Work out the fee. Under rule 15, up to 25,000 borrowers the certificate fee is Tk 10,000 and the annual fee Tk 5,000; from 25,000 to 1 lakh borrowers it is Tk 25,000 and Tk 10,000.
- 5Raise the loan fund. In June 2025 the sector's funds came 40.07 percent from members' savings, 33.98 percent from accumulated surplus, 11.05 percent from commercial bank loans and 6.95 percent from PKSF.
- 6Form groups, enrol members and issue pass books. Under Circular Regu-23 the admission fee is Tk 10, the pass book Tk 10 and the loan form Tk 5 — Tk 25 in all, and not a taka more.
- 7Set and display the service charge. The ceiling is 24 percent on the declining balance; a 'flat' rate on equal instalments is a different number, so tell members which method you are using.
- 8Keep members' savings in a separate account. Section 32(1) bars deposits from anyone who is not a member, and every deposit must be entered in the pass book on the spot.
- 9Run the branch bank account on the joint signature of two authorised officers, as rule 14(10) requires, and keep hard copies of the general ledger and cash book.
- 10Catch arrears on collection day. MRA counts 1-30 days overdue as watchful, 31-180 as substandard, 181-365 as doubtful and over 365 days as bad.
- 11Keep at least 70 percent of your clients as borrowers, as rule 13(3) requires. Piling up savings-only members breaks the condition.
- 12Pay the annual fee, send the audit report and the updated board list to MRA every year, and maintain the loan loss provision.
Seasons
- JanNormal
- FebNormal
- MarNormal
- AprNormal
- MayNormal
- JunNormal
- JulNormal
- AugNormal
- SepNormal
- OctNormal
- NovNormal
- DecNormal
Where it works well
- Strong fitBogura · 771 branches and Tk 47.61 billion outstanding, the highest in Rajshahi division, with borrowers high relative to members, meaning few dormant accounts.
- Strong fitChattogram · 1,278 branches and Tk 79.01 billion outstanding, with a savings balance of Tk 41.69 billion that is strong relative to lending.
- Strong fitCumilla · 1,285 branches and Tk 105.28 billion outstanding, second only to Dhaka. Remittance and trading money make loan sizes larger here.
- Strong fitDhaka · The country's largest microcredit market: 1,553 branches and Tk 113.75 billion outstanding in June 2025, more than any other district. Demand is proven and so is the competition.
- Strong fitGazipur · 816 branches and Tk 59.15 billion outstanding. Factory worker households and rented settlements give the density that weekly collection needs.
- PossibleDinajpur · 714 branches and 999,402 borrowers. Rangpur division's pattern is many members but small loans: it holds 12.61 percent of the country's borrowers but only 9.64 percent of outstanding.
- PossibleMymensingh · 621 branches and Tk 38.24 billion outstanding. All of Mymensingh division's indicators cluster at 4-5 percent: a small but stable market.
- PossibleNaogaon · 723 branches and Tk 39.24 billion outstanding. Matching instalment dates to paddy and potato income is the local problem.
- PossiblePabna · 671 branches and Tk 40.15 billion outstanding, with handloom, dairy and small trade creating demand for microenterprise loans.
- Weak fitBandarban · The lowest in the country: 38 branches and 51,305 borrowers. Distance and scattered settlement make weekly collection too costly to cover.
- Weak fitSunamganj · Only 167 branches. Sylhet division holds just 3.19 percent of the country's branches, and MRA's own explanation is that remittance income reduces dependence on microcredit here.
Risks and cautions
- HighCompliance: A new certificate cannot be had. MRA's public notice of 4 November 2024 suspended acceptance of new applications until further order. The same notice records 898 certificates against 6,642 applications ever received - fewer than one in seven - with 174 later cancelled and 724 surviving. Operating without a certificate is punishable under section 35 by up to one year in prison, a fine of up to Tk 5 lakh, or both. Anyone opening a samity today and lending at interest is committing an offence, not merely an irregularity.
- HighWorking capital: Money is out for about 231 days on average. MRA's June 2025 figures show Tk 82,251 disbursed and Tk 51,921 outstanding per borrower, so the fund turns only 1.58 times a year. Every new member adds pressure, and when savings withdrawals (Eid, school admissions, weddings) coincide with fresh disbursement the branch runs dry.
- HighLate payment: Recovery is worsening fast. Classified loans were 8.52 percent of outstanding in June 2025 against 8.09 percent a year earlier. The real warning is elsewhere: watchful loans, 1-30 days overdue, went from 1.12 to 8.85 percent, nearly eightfold, and MRA itself says a share of these may migrate into the classified categories. Bad loans over 365 days already stand at Tk 82.21 billion.
- MediumDemand: The margin is thin and capped by law. Revenue tops out at Tk 24 per Tk 100 outstanding while the big institutions spend Tk 14.55 to 19.59. Small institutions usually cost more, because the same staff serve fewer members. The 24 percent ceiling cannot be lifted, so the only routes to profit are lower cost or more members.
- MediumCompliance: Small breaches cost the certificate. Working outside the approved area, taking deposits from non-members, charging more than Tk 25 for admission and pass book, or letting borrowers fall below 70 percent of clients are each rule violations. MRA may suspend a certificate for up to 12 months after a hearing, and without a hearing where the public interest requires. 174 certificates have already been cancelled.
Sources
সিটি কর্পোরেশন থেকে ট্রেড লাইসেন্স প্রাপ্তির ধাপ সমূহ
Collected: 16 Sept 2026Supports: Starting capital · বাংলাদেশ
Microfinance in Bangladesh (Annual Statistics), June-2025
Collected: 31 Jan 2026Supports: Starting capital, Cash cycle, Gross margin, Monthly working capital, Variable cost, Waste / loss · বাংলাদেশ
এমআরএ/সার্কুলার লেটার নং-৫০: ক্ষুদ্রঋণের সার্ভিস চার্জের হার পুনঃনির্ধারণ প্রসঙ্গে
Collected: 9 Sept 2019Supports: Gross margin, Selling price · বাংলাদেশ
মাইক্রোক্রেডিট রেগুলেটরী অথরিটি বিধিমালা, ২০১০ (এস.আর.ও নং ৩৯৪-আইন/২০১০) — বিধি ৪, ১৩, ১৪ ও ১৫
Collected: 19 Dec 2010Supports: Starting capital · বাংলাদেশ
What changed
No corrections have been published yet.
Questions and answers
No questions yet. Be the first to ask.
Stories about this business
1,400 taka a month per lakh, two and a half crore taken in, and the secretary gone
A cooperative society formed in Bagerhat in 2015 took in about 2.5 crore taka on a promise of 1,400 taka a month per lakh; its secretary vanished in April 2022, with roughly 70 lakh still out on loan.
- Reasons
- Other, Partner dispute
Similar businesses
 Digital & B2B services
Travel agency
Tickets, visas and hajj-umrah packages. Ministry registration costs Tk 62,500, renewal Tk 25,000 every three years, and the 2026 ordinance requires a Tk 10 lakh bank guarantee.
- Capital
- ৳12 lakh – ৳25 lakh
- People
- 2 – 8
- First income
- 45 – 120 days
 Digital & B2B services
Money exchange
Buying and selling foreign currency notes under a Bangladesh Bank licence. On 21 September 2026 the dollar was bought at Tk 125.60 and sold at Tk 126.60 — one taka a dollar. Doing this without the licence is a criminal offence carrying up to seven years in prison.
- Capital
- ৳10 lakh – ৳45 lakh
- People
- 2 – 6
- First income
- 90 – 365 days
 Digital & B2B services
Truck and pickup hire
Carrying goods for hire by truck or pickup. Diesel is government-priced at Tk 115 a litre, but there is no government freight list - the rate is whatever you can bargain.
- Capital
- ৳5 lakh – ৳30 lakh
- People
- 2 – 4
- First income
- 15 – 45 days
 Digital & B2B services
Tour operator
Running organised tours. It is not lawful without registration from the Bangladesh Tourism Board, and the 2024 rules require a Tk 300,000 non-refundable fee, a Tk 1,000,000 bank solvency certificate and a Tk 50,000 security deposit with the application.
- Capital
- ৳3.5 lakh – ৳15 lakh
- People
- 2 – 12
- First income
- 90 – 365 days